

Last updated on 06 March 2026
If you’re already thinking about this, you’re heading in the right direction! Here at Yield, we’ve had lots of conversations with clients just like you, wondering: How much do I need to retire on $80,000 a year or is $80,000 a year enough for retirement? It’s not just about the number; it’s about imagining the life you’ve been dreaming of.
So, let’s start with a straight answer:
- If you want to retire on $80,000 a year and if you’re not expecting any Centrelink support, you’ll likely need around $1.43 million.
- With Age Pension support factored in, you may need about $662,536.
However, that doesn’t necessarily mean it’s the right number for you. Keep reading to get a deeper understanding and to think more deeply about whether $80,000 is indeed the right retirement income for you.
Key Considerations for How Much Do I Need Retire on 80 000 a Year in Australia
1. Your Desired Retirement Lifestyle
Before you lock in on a retirement income number, have you really thought about the kind of life you want when you retire? Will you travel around the world? Explore hobbies you’ve always wanted to try? Or maybe you’re keen on leaving something special behind for your family or supporting causes close to your heart? These desires really impact how much money you’ll need to have saved up and the clearer your vision is, the easier it is to plan for your $80,000 retirement.
While $80,000 sounds like a decent retirement income, let’s take a closer look at how it aligns with the average living standards in Australia. According to ASFA’s latest data,
- for couples aged 65-84, aiming for a modest lifestyle, the recommended annual budget comes to around $51,299. Singles, on the other hand, are advised to budget around $35,503 per year.
- However, if you’re aiming for a more comfortable retirement, the figures increase to $77,375 for couples and $54,840 for singles annually.
These insights offer valuable perspective on what it takes to maintain financial stability during retirement in Australia and points to $80,000 being a better than average retirement standard.

Let’s keep in mind that these figures are just averages. Your retirement income target will be shaped by your unique lifestyle preferences and circumstances. When we advise our clients about their income goals, we always start by asking them to imagine what their dream retirement looks like.
First step is to calculate if everything is achievable, and if it is, then that’s fantastic! But if the numbers don’t quite add up, then that’s when we can get creative. What is most important to you for example. Maybe you’re keen on traveling more in the early years of retirement and are open to adjusting your income later on. The key here is personalisation. Your retirement plan is deeply personal. So, take a moment to think about the kind of retirement you’ve always dreamed of. And if you ever feel overwhelmed or unsure about how to turn those dreams into reality, don’t hesitate to reach out to retirement experts.

2.Deciding on Your Retirement Age and Factoring Life Expectancy
When thinking about life expectancy, it’s not as clear cut as it might seem. As a starting point however, data from the Australian Bureau of Statistics states that men usually live to 81, while women often reach 85. But here’s the thing: these numbers aren’t set in stone. They shift based on when you plan to retire. Plus, if you’re in a financially dependent relationship, it’s crucial to consider the life expectancy of the younger partner.
Naturally, the longer you expect to live, the more money you’ll need to cover your expenses. At Yield, we’re all about looking ahead. We project our figures to age 90, creating flexibility to adjust the strategy if needed down the line. By factoring life expectancy into your retirement planning, you can ensure your financial stability well into your golden years.

3.Age Pension
When it comes to planning your retirement on $80,000 a year, it’s essential to consider all your financial resources. While the Age Pension isn’t designed to be your sole income source, it can serve as a valuable safety net within your retirement plan. Meeting specific age and residence criteria, as well as passing income and asset tests, determines your eligibility. Understanding these requirements is key to determining if and how much Age Pension you might receive.
Interestingly, around 70% of retirees in Australia currently receive partial amount of Age Pension support. This statistic holds relevance, particularly when contemplating a retirement income goal of $80,000 per annum. Even with this target in mind, there’s a possibility that as your investment reserves diminish over time, you may become eligible for Age Pension benefits.
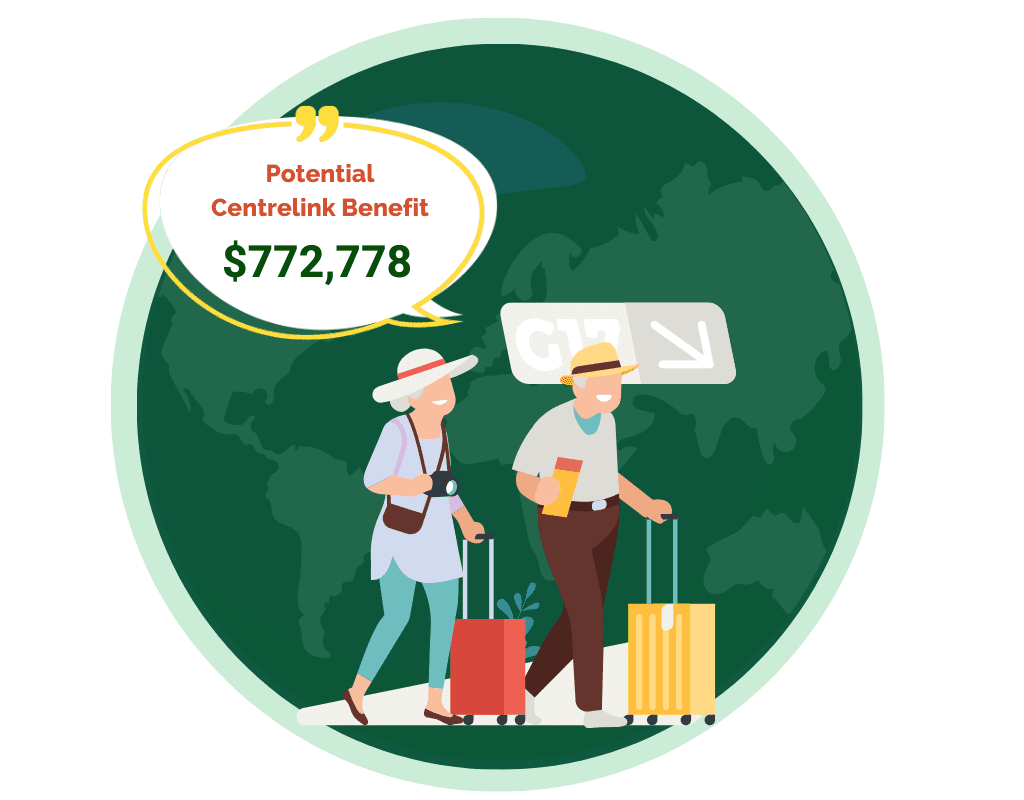
Our analysis further in this blog reveals that Centrelink entitlement could potentially provide substantial additional support amounts of up to $772,778 if your financial investments are entirely depleted. This underscores the significant impact Age Pension entitlements can have on your retirement income strategy. For a comprehensive understanding of Age Pension eligibility criteria and potential benefit amounts relevant to your retirement objectives, you can read our latest blog: Can I Get the Age Pension.
4. Your Current and Future Expenses
Understanding both your present and future expenses is important for ensuring a comfortable retirement with $80,000 a year. Think about how things might change over time – like healthcare costs, inflation, and whether you might downsize your living space. Keeping an eye on your spending habits, researching what costs might come up down the road, and staying open to adjustments can really help you stay on track. While some assumptions can be made for variables like inflation, planning for events like downsizing can have a real impact your financial future.
5. Your Debt Levels
Having a lot of debt when you retire can really throw a wrench in your plans. It might mean you have less money to enjoy those golden years. So, it’s a smart move to tackle those high-interest debts before you retire. This can ease stress and give you more freedom within your budget. By actively managing and reducing debt both before and during retirement, you can set yourself up for a smoother financial ride and make that $80,000 a year stretch a little further with more security.
6. Your Super Balance
Your super balance is likely to be your primary income source during retirement. How much you have in super, will therefore determine how much money you’ll have to live on, and the way your funds are managed and invested will influence how long your savings will last. So, when you are thinking about, how much super do I need to retire on $80 000 a year, it’s essential to keep a close eye on your super savings.
Superannuation is specifically designed for retirement, offering tax-free benefits and acting as a reliable income source. Therefore, it’s worth looking into ways to boost your super before you retire. By growing your super wisely, you can make sure your retirement funds last longer, giving you the peace of mind to enjoy a comfortable retirement on $80,000 a year.
Let’s Talk Numbers: How Much Do I Need to Retire on $80 000 a Year?
Based on our calculations for a couple aged 67-90 planning to retire until age 90, here’s the estimated lump sum you’d need today to generate a comfortable retirement income of $80,000 per year:
- Without Centrelink benefits: approximately $1,435,314
- With Centrelink benefits: approximately $662,536
These figures assume your savings are invested within superannuation and converted to pension phase, meaning investment earnings and withdrawals are tax-free.
As you can see, Centrelink benefits could contribute around $772,778 in additional income support over your retirement, significantly reducing the lump sum you need to have saved.

While these figures provide a helpful starting point, it’s essential to remember that they’re based on assumptions and may not perfectly align with your individual circumstances. Therefore, when you’re crafting your retirement plan and pondering, how much do I need to retire on $80 000 a year? it’s crucial to consider all relevant factors.
To personalise these calculations, you should seek guidance from a retirement specialist. They can give you tailored advice and help craft a retirement plan that’s just right for you, considering all the little details that make your situation unique.
Why Choose Yield?
At Yield, we recognise that retirement isn’t just another chapter, it’s a defining moment in your life that needs utmost care and attention. We also know how overwhelming it can be to plan for it, with so many things to consider. But you are not alone in this journey. With Yield, you will get a different approach, one that’s all about you. We take the time to really understand your needs and dreams, creating a retirement plan that fits just for you.